In 2010, a couple in a nine-story Chelsea building stopped paying rent. Not because they couldn't afford it. Because their landlord, whose building was mostly commercial, had never obtained a residential certificate of occupancy for the unit they lived in. Six years later, that landlord was still trying to collect $410,000 in back rent on what had been a $4,754.02 monthly lease. Housing attorneys who spoke to Brick Underground about the case said the tenants were likely to come out ahead, because without that document, the landlord had no legal right to collect rent in the first place.
Read as a renter's story, that's a loophole. Read as a buyer's story, the same missing document means something else entirely. What protects a tenant against a landlord can quietly stop a bank from lending to you at all.
The Same Gap, Two Different Outcomes
A tenant living in an apartment without a residential certificate of occupancy has leverage. The building's own paperwork failure becomes their defense against eviction and, in some cases, their reason not to pay rent at all. A buyer walking into that same building has the opposite problem. Banks need at least a temporary certificate of occupancy to issue financing, full stop, regardless of the buyer's credit, income, or down payment. If the building never secured even a temporary one, a conventional mortgage isn't slow to arrive. It isn't coming.
That distinction matters more in Chelsea than in most Manhattan neighborhoods, because Chelsea has a specific kind of building stock where this exact gap shows up.
Why This Shows Up in Chelsea Specifically
Chelsea, along with SoHo and Tribeca, is one of the neighborhoods the New York City Loft Board points to when explaining how its own jurisdiction came about. Through the 1970s, landlords in these manufacturing districts let tenants move into buildings that were zoned for commercial and industrial use, and by 1977 the city's own Department of City Planning found that 91.5 percent of those conversions were illegal, with nearly half of the units occupied by artists who had built out the raw space themselves.
The 1982 Loft Law was the city's attempt to catch up with what had already happened on the ground. It created a new category, the Interim Multiple Dwelling, for buildings that had residential tenants but no residential certificate of occupancy, and it gave landlords a legal path to bring those buildings up to code over time. That path has historically taken ten to twenty years per building, start to finish, according to attorneys who handle these legalizations. A conversion that started in the late 1970s in Chelsea's old warehouse blocks could easily still be working through that process today, decades and several ownership changes later.
This is the building type buyers picture when they picture a Chelsea loft. The Campiello Collection at 151 West 17th Street and the units known as Chelsea Mews are the kind of address that shows up when people search for exposed brick and open floor plans west of Sixth Avenue. Buildings like these are simply examples of the housing stock born from that era of industrial-to-residential conversion, and the point isn't that any specific one of them has a paperwork problem today. It's that the building type itself carries a different kind of risk than a new condo tower, and most generic buyer guides don't draw that line.
As one attorney explained to Brick Underground, "the loft law was created as a disincentive for commercial landlords to put residential tenants into buildings" in the first place, not to make legalization easy after the fact.
Two Kinds of Missing Paperwork
Most articles about certificate of occupancy problems in New York are actually describing a different, more common situation: a brand new condo building where the sponsor closes sales before the final sign-off arrives. That gap is real, but it behaves nothing like a legacy loft gap.
| New-development gap | Legacy loft/IMD gap | |
|---|---|---|
| Typical building | Recently completed condo | Pre-1982 manufacturing conversion |
| What's missing | Final C of O, but a valid TCO usually exists | Any residential C of O at all |
| Usual fix | Sponsor resolves outstanding punch-list items and files for sign-off | Loft Board legalization process, often an Alt-1 filing and years of construction |
| Typical timeline | Weeks to a few months | Ten to twenty years, sometimes longer |
| Financing impact | Most lenders will close with a valid TCO in hand | Conventional lenders often decline outright |
The first kind is an inconvenience with a visible end date. The second is a structural condition of the building that doesn't resolve on any closing timeline you can plan around.
What This Does to Your Financing
The distinction shows up the moment you apply for a mortgage. A lender working with a new-development TCO just needs it verified and confirmation it won't expire before closing, which is a routine underwriting step. A lender looking at a building with no C of O at all, and no clear date for one, generally walks away from the deal.
Buyers who still want the apartment are left with narrower options: an all-cash purchase, or a portfolio lender willing to take on the added risk at a higher rate than a conventional bank would offer. Neither path is unusual in Manhattan's older loft stock, but both change the math on a purchase that looked straightforward when you were only comparing price per square foot.
Timing compounds the problem. Buyers typically lock a mortgage rate for 60 to 90 days. Confirming a building's Loft Board status, and whether any legalization work is even in progress, can eat weeks of that window before you've learned anything definitive. Miss the lock and you're either paying weekly extension fees or restarting at whatever the market rate happens to be by then.
Before You Write the Offer
A few steps catch most of this before it becomes a problem instead of a question:
- Pull the building's certificate of occupancy record from the city's Building Information System before you go to contract, not after you're already under one.
- Ask your attorney to check whether the building, or your specific unit, was ever registered with the Loft Board as an Interim Multiple Dwelling.
- Ask how the last two or three sales in the building were financed. A pattern of all-cash closings is itself an answer worth taking seriously.
- Get your lender to confirm in writing that they will lend on this specific building, not just approve you as a borrower, before you waive a mortgage contingency to compete for the apartment.
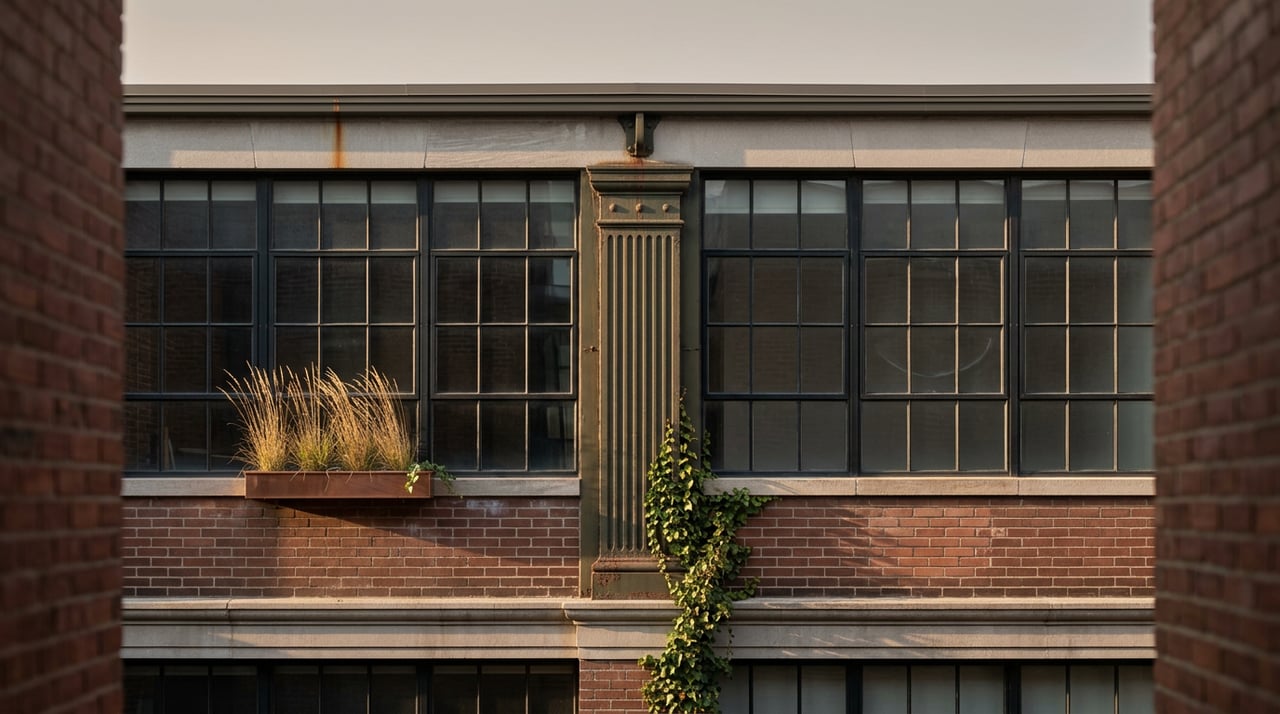
Exposed brick, steel casement windows, and twelve-foot ceilings tell you a great deal about how a Chelsea loft will feel to live in. They tell you nothing about whether the city considers it legal to live in yet. Only the paper does, and the paper is where the real due diligence starts.
FAQ
Does this only affect true raw lofts, or can it touch condos and co-ops too? The Interim Multiple Dwelling framework applies to residential use inside buildings originally certified for commercial or manufacturing use. Some co-op and condo conversions were built directly on top of that same industrial stock, and an offering plan doesn't erase a Loft Law history if the underlying building was never brought fully into compliance.
If a building is a registered IMD still working through legalization, can I get a mortgage at all? Sometimes, but expect a smaller pool of willing lenders and more scrutiny of exactly where the building sits in that legalization timeline. Given that the process has historically run ten to twenty years, some buildings change hands several times before it's ever complete.
Does paying cash just make this go away? Cash removes the lender's requirement for a certificate of occupancy, but it doesn't remove the underlying exposure. Occupancy status can still affect insurance, how the space is legally allowed to be used, and how easily you can resell to a buyer who needs financing.
How do I actually check a Chelsea building's certificate of occupancy before making an offer? The Department of Buildings' public Building Information System lets anyone search an address and view any certificate of occupancy on file for it. From there, an attorney can go further and check Loft Board registration history and any open legalization filings tied to the property.
Chelsea's loft buildings are some of the most distinctive housing stock in Manhattan, and most of them come with clean paperwork and straightforward financing. The ones that don't are rarely obvious from a listing photo. If you're weighing a Chelsea loft and want a second set of eyes on what the building's history actually says before you write an offer, Frances Katzen and her team spend their days inside exactly these buildings. Get in touch before you fall for the space and skip the paper.